

BCBA liability insurance is one of the least discussed parts of a behavior analyst's job package. Most BCBAs assume their employer's policy protects them, and many never check. Yet when we read 688 ABA employers' BCBA job ads in October 2026, only 13 said they pay for the BCBA's professional liability coverage. This guide explains when a BCBA needs a personal policy, what a typical policy covers (including BACB and licensing board complaints), how to compare quotes, and the questions to ask an employer before you sign an offer.
Do BCBAs need liability insurance?
We found no BACB rule requiring certificants to carry malpractice insurance, and no single law requires it of every BCBA. Whether you need your own policy depends on how you work. Many ABA employers carry a policy that also covers clinicians for work done within their job. But an employer's policy is written to protect the employer first. It may not name you, it may not pay for your own lawyer in a board complaint, and it does not follow you to work you do for anyone else.
| How you work | Do you need your own policy? |
|---|---|
| W-2 employee, one employer, no outside work | Optional. Confirm in writing that the employer's policy covers you and includes licensing board defense. |
| W-2 job plus PRN, consulting or a second employer | Strongly recommended. Each employer's policy covers only its own work. |
| 1099 independent contractor | Yes. Contractors are usually outside the client company's policy, and many contracts require a certificate of insurance. |
| Private practice or in-network with health plans | Yes. Payer credentialing asks for proof of professional liability coverage and its limits. |
| Supervising fieldwork trainees outside your employer | Recommended. Independent supervision is your own professional service. |
CPH Insurance, one of the carriers that writes BCBA policies, puts the contractor point plainly on its BCBA page: an independent contractor "will likely not be covered" by an employer's policy. If you are weighing contract work, our BCBA staffing agency guide covers how W-2 and 1099 placements differ.
What BCBA liability insurance covers
A BCBA professional liability policy pays for your legal defense and any settlement or judgment if a client, caregiver or third party claims your professional services caused harm. The common claim scenarios carriers describe are allegations about a behavior intervention, a client injured during a session, boundary or dual-relationship issues, a client who did not make expected progress, and supervision claims, where a BCBA is named because a technician they supervised made an error.
That last one matters more in ABA than in most fields. As of October 8, 2026, the BACB's registry listed 274,233 RBTs in the United States and 81,523 BCBAs and BCBA-Ds, about 3.4 RBTs for every BCBA. Most BCBAs carry supervisory responsibility for someone else's sessions.
Here is what three carriers' published BCBA policies included when we checked their sites on October 8, 2026:
| Feature | CPH Insurance | CM&F Group | The Trust |
|---|---|---|---|
| Policy form | Occurrence | Occurrence | Occurrence |
| Liability limits | Not listed (optional general liability $1M / $3M) | Up to $1M per claim, up to $6M aggregate | $1M / $3M standard |
| Licensing board defense | $35,000 | Up to $35,000 per claim, $100,000 aggregate | Included |
| Deposition expenses | $10,000 per deposition | Up to $25,000 | Included |
| Other notable terms | Assault $15,000; telehealth within limits | HIPAA defense up to $35,000; you must consent to any settlement | No deductible; defense costs paid in addition to limits |
HPSO also writes coverage for applied behavior analysts, with individual limits up to $1 million per claim and $3 million aggregate. Sublimits and wording change, so treat the table as a starting point and read the actual policy before you buy.
Occurrence vs. claims-made
An occurrence policy covers an incident that happened while the policy was active, even if the claim arrives years later. A claims-made policy covers only claims filed while the policy is active, so when you cancel it you need "tail" coverage to protect past work. All three carriers above sell BCBA policies on an occurrence form. Employer policies are a different story: ask which form your employer's policy uses, because if it is claims-made, your protection for past work depends on that employer keeping its coverage after you leave.
Does it cover BACB ethics complaints?
Lawsuits are not the only risk, and often not the most likely one. The BACB's Ethics Department accepts a Notice of Alleged Violation from anyone concerned that a certificant broke its ethics requirements, and in states that license behavior analysts, a complaint can also go to the state board. Both can threaten your ability to work, and both are cheaper to answer with a lawyer.
Most BCBA policies include a "licensing board defense" or "regulatory defense" benefit that pays legal costs separately from your liability limits. Check the wording, because the BACB is a certification board, not a state licensing agency. CM&F says that with its policy, "if a complaint is filed with the BACB or your state licensing board, you have an attorney to represent you without drawing from your malpractice limits." CPH's page lists "State Licensing Board Defense." If certification-board complaints are not named in the policy, ask the carrier in writing before you buy.
What employers say about liability coverage in BCBA job ads
We searched 688 BCBA job ads, one per direct ABA employer, drawn at random from listings collected on LinkedIn and SimplyHired on October 1, 2026, for any mention of malpractice or professional liability insurance. Then we read every match. Only 13 employers (1.9%) listed employer-paid professional liability insurance as a benefit. Two more did the opposite and listed "current malpractice insurance" or "professional liability insurance coverage" among the BCBA's own qualifications.
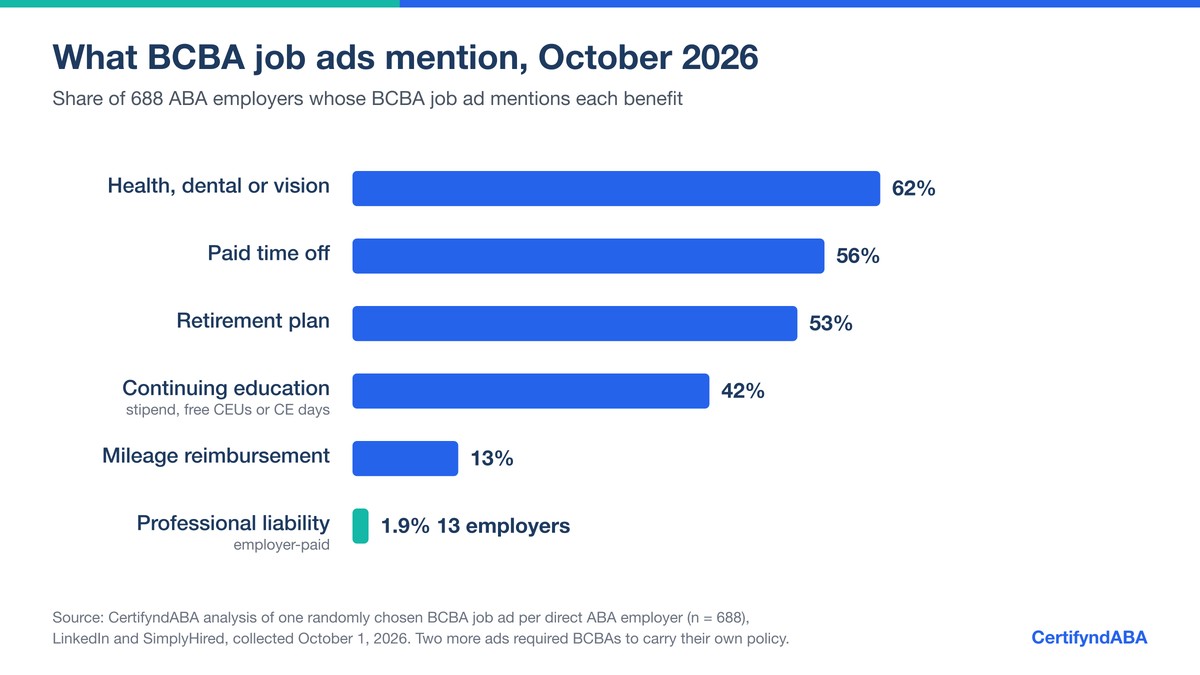
For comparison, the same ads mentioned health, dental or vision coverage 62% of the time, paid time off 56%, a retirement plan 53%, and mileage 13%. In our free BCBA CEUs analysis of the same ads, 42% offered a continuing education benefit. Employers that did mention liability coverage tended to list it next to other professional costs, such as "Employer-paid professional liability insurance" alongside a CEU stipend (Neurobehavioral Center for Growth), or "Professional liability insurance covered" in the same list as paid recertification and licensure renewal (Lighthouse Autism Center).
A missing line in a job ad does not mean you are uninsured. Many ABA employers insure their clinicians and simply do not advertise it. It does mean you have to ask, because the ad will not tell you.
Questions to ask before you accept a BCBA offer
- Am I covered by the company's professional liability policy, and am I a named or additional insured?
- What are the limits, and are they shared across every clinician in the company?
- Is it an occurrence or a claims-made policy? If claims-made, who pays for tail coverage if I leave?
- Does it pay for my own attorney in a BACB Notice of Alleged Violation or a state licensing board complaint?
- Does it cover telehealth sessions and supervision of trainees I take on through the company?
- Can I get a certificate of insurance? It is the simplest proof that coverage exists.
If the answers are vague, budget for your own policy. If the employer does not cover you at all, it is a reasonable item to raise in negotiation. Demand is on your side: Lightcast counted 132,307 US job postings for BCBAs in 2025, about 1.6 postings for every active US BCBA and BCBA-D. That ratio compares a year of postings with a one-day head count, so it is not a count of open jobs, but it shows how much competition there is for your time. Our BCBA salary negotiation guide covers how to raise benefits alongside pay.
How to buy BCBA liability insurance
None of the carrier BCBA pages we checked lists a price; premiums depend on your state, limits and practice setting. Most let you get a quote online in a few minutes and download proof of coverage once you pay. When you compare quotes:
- Match the limits to your contracts. $1 million per claim and $3 million aggregate is the standard limit at The Trust and HPSO. If you credential with health plans or contract with a school district, check its minimums before you buy.
- Look for discounts. The Trust lists 50% off for newly licensed professionals in their first year and for part-time practice of 24 hours or less a week, plus smaller discounts for continuing education, switching carriers and applying online, with a combined cap of 50% and a minimum premium.
- Compare the extras, not just the price. Board defense limits, deposition coverage, HIPAA coverage and whether defense costs reduce your limits matter more than a small premium difference.
- Add general liability if you see clients in your own space. Professional liability covers your services; general liability covers a slip-and-fall in your office.
Starting a practice? Our guide to starting an ABA therapy practice covers the business insurance and credentialing steps that come with it.
Frequently asked questions
Is liability insurance required for BCBAs?
We found no BACB requirement. It becomes required in practice when a payer, a school district, a contracting agency or a client contract asks for proof of coverage, which is standard for private practice and 1099 work.
Does my employer's insurance cover me as a BCBA?
Often, for work you do within your job, but not always and not for work outside that employer. Ask whether you are named on the policy, what the limits are, and whether it pays for your own attorney in a board complaint.
Does BCBA malpractice insurance cover BACB ethics complaints?
Many policies include licensing or regulatory board defense that pays legal costs outside your liability limits. Some name state licensing boards only, so confirm in writing that certification-board complaints are covered.
Do 1099 BCBAs need their own malpractice insurance?
Yes. Independent contractors are generally outside the client company's policy, and many contracts require a certificate of insurance before you start.
What coverage limits should a BCBA carry?
$1 million per claim and $3 million aggregate is the standard limit at carriers such as The Trust and HPSO; CM&F offers up to a $6 million aggregate. Check any payer or contract minimums before you buy.
How many ABA employers pay for BCBA liability insurance?
In our October 2026 review of 688 employers' BCBA job ads, 13 (1.9%) advertised employer-paid professional liability insurance. Many more likely provide coverage without advertising it, so ask during the interview.
The bottom line
If you only work as a W-2 employee for one employer, BCBA liability insurance is a question to ask, not necessarily a policy to buy. Get the answers in writing and check that board complaints are covered. If you take PRN shifts, consult, contract, supervise independently or run a practice, carry your own occurrence policy. And when you compare offers, count liability coverage, board defense and recertification costs as part of the package, because almost no employer will mention them unless you ask.
Let employers compete for you
CertifyndABA is an anonymous reverse job marketplace. Showcase your verified BCBA credential and let ABA employers send you interview requests with pay ranges up front.
Create Your Free Profile